
Mumbai property guide
India's financial capital — record office absorption, ₹3-trillion ring-road network, and the only Indian metro where infrastructure (not pricing) is currently the biggest story.
Mumbai property market today
Market pulse
Mumbai's 2026 market is infrastructure-led, not price-led. Square Yards data shows asking prices at ₹38,597/sqft as of March 2026, with actual government-registered transactions averaging ₹18,130/sqft — a 53% gap that reflects the structural reality of redevelopment-zone Mumbai. The market recorded 101,805 transactions worth ₹1,58,172 Cr between May 2025 and April 2026 (Maharashtra IGR data) — making it India's deepest residential market by transaction value.
The story is uneven by submarket. Mumbai South commands ₹46,342/sqft (highest), Mumbai Harbour ₹36,015, Western Suburbs ₹34,583, Central Suburbs ₹32,882. Premium pockets — Worli, Malabar Hill, Bandra West, Juhu — cross ₹55,000–1,20,000/sqft for sea-facing inventory. Mid-premium corridors like Mulund, Thane and parts of Powai sit at ₹22,000–32,000 — Cushman & Wakefield reports the mid-segment dominated Q1 2026 launches at 48% share.
The infrastructure dividend is actively being paid out right now. Atal Setu (MTHL, opened Jan 2024) cut South Mumbai-to-Navi Mumbai commute from 90+ min to ~20. Metro Line 3 (Aqua Line, fully operational mid-2025) connects Cuffe Parade to Aarey via BKC. Coastal Road Phase 2 (Bandra-Kandivali, ~19 km) targets May 2026 completion. Metro Line 4 (Green Line, Wadala-Kasarvadavali) phased commissioning since Dec 2025. Plus office leasing hit a record 6.6 MSF in Q1 2026 with BFSI at 44% share and GCCs at 30%+.
Get the Mumbai price report
Live prices straight from developer price sheets, not listing portals.
- Rate per Sq.Ft. and all-in price for each project
- Upcoming launches before they open
- Current offers and payment plans
Where should we send it?
Sent to your phone within 30 minutes, 9 AM to 9 PM.
Where to buy in Mumbai
Every area guide we publish, with average rates and live project counts.
Old-money Mumbai — Malabar Hill, Worli, Bandra. ₹55,000–1,20,000/sqft, ultra-premium pricing, address-value-driven, not appreciation-driven.
Mulund, Powai, Ghatkopar, Chembur — ₹22,000–32,000/sqft entry, anchored by Metro Line 4 (Wadala-Thane) and GMLR completion 2026.
Atal Setu-anchored, NMIA-anchored expansion — Thane, Panvel, Kharghar, Ulwe. ₹15,000–22,000/sqft entry, highest medium-term upside.
Find your area in Mumbai
Start from who you are, not from a map. Our picks for the most common buyer profiles.
BFSI / corporate professional working at BKC, Worli or Lower Parel
Walk-to-work or 15-min commute, deep secondary-sale liquidity, Metro Line 3 fully operational since 2025.
IT professional working at Powai, Vikhroli, or BKC
Metro Line 4 cuts BKC commute by 50–75%, mature schools/hospitals, ₹22,000–32,000/sqft entry vs ₹40,000+ in western suburbs.
Family with school-going children seeking premium gated communities
International schools (TISB, Ecole Mondiale, NES), tertiary hospitals (Hiranandani, Fortis), greenery — all walkable.
Long-horizon investor seeking maximum upside (5–7 year)
NMIA opens Phase 1 May 2025, Atal Setu is operational, VAMC corridor expected 2030 — pre-airport pricing window closing fast.
First-time buyer on ₹1–2 Cr budget
2 BHK inventory at ₹1.2–2 Cr in metro-connected zones, RERA-active branded developers, infrastructure catalysts ahead.
Ultra-premium / luxury buyer (₹10 Cr+)
Sea-facing inventory at ₹55,000–1,20,000/sqft from Lodha, Oberoi, Piramal — 24% of buyers are now from outside Mumbai (Delhi, Bangalore, Dubai, London).
Latest projects in Mumbai
Recently added launches from 27 live projects across the city.
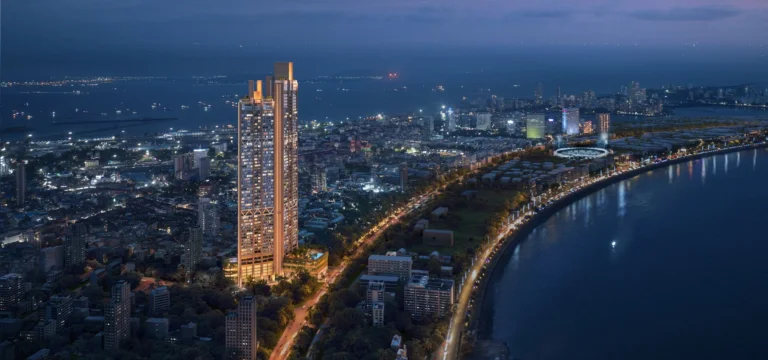

Looking at 27 projects is a lot.Tell us your budget and commute and get the best 3 to 5 on one call.
Most active builders in Mumbai

 Godrej Properties50 projects
Questions buyers ask about Mumbai
Is Mumbai a good city to invest in real estate in 2026?
Yes — but with discipline. Mumbai is India's deepest residential market (₹1.58 lakh Cr in transactions May 2025–Apr 2026, 1.01 lakh registrations) and its most infrastructure-anchored. The question isn't whether to invest but where: South Mumbai/Worli/Bandra are address-value plays with 4–6% appreciation; Western Suburbs (Andheri-Borivali) carry the bulk of activity at 8–10%; Central Suburbs (Mulund/Powai) and Thane/Navi Mumbai offer 12–18% appreciation runways via Metro Line 4 + Atal Setu + NMIA catalysts. The watch-out: at ₹38,597/sqft asking and a 53% govt-registration gap, the easy money has been made in established submarkets.
Which area is the best to buy in Mumbai?
Depends on priorities. For BFSI/corporate professionals, Lower Parel, Worli and Bandra West offer walk-to-work or 15-min commute. For IT workers, Mulund, Powai and Vikhroli get Metro Line 4 + walk-to-work proximity at ₹22,000–32,000/sqft. For long-horizon investors, Panvel, Ulwe and Kharghar are pre-NMIA-completion pricing windows. For first-time buyers, Thane West and Mulund West offer 2 BHK at ₹1.2–2 Cr in metro-connected zones. For premium buyers (₹10 Cr+), Malabar Hill, Worli and Bandra West dominate.
What is the average property price per sqft in Mumbai in 2026?
Asking prices average ₹38,597/sqft (Square Yards Mar 2026), up from ₹35,552 in September 2025. Actual government-registered transactions average ₹18,150/sqft — typical for redevelopment-heavy Mumbai. By zone: Mumbai South ₹46,342, Mumbai Harbour ₹36,015, Western Suburbs ₹34,583, Central Suburbs ₹32,882. Premium areas (Worli, Bandra West, Malabar Hill) cross ₹55,000–1,20,000/sqft for sea-facing inventory. Affordable corridors (Thane, Panvel, parts of Mulund East) are at ₹15,000–22,000/sqft.
How much does a 2 BHK flat cost in Mumbai in 2026?
Affordable areas (Panvel, Ulwe, Bhiwandi, Mira-Bhayandar): ₹60 lakh–₹1.2 Cr. Mid-segment metro-anchored corridors (Thane West, Mulund West, Goregaon, Kandivali): ₹1.5–2.5 Cr. Premium residential (Bandra West, Worli, Lower Parel): ₹3–6 Cr+. Average 2 BHK rent across Mumbai is ₹83,561/month per Square Yards. Add 8–10% to your purchase price for stamp duty (5%), registration and ancillary costs.
How does Mumbai compare to Bengaluru and Hyderabad for real estate investment?
Different value propositions. Mumbai is the prestige market — India's deepest transaction depth, highest absolute pricing (₹38,597 vs Bengaluru ₹12,119 vs Hyderabad ₹9,430), best resale liquidity, address-value premium for HNIs (24% of luxury buyers come from outside the city). Bengaluru wins on consistent 5-year appreciation in IT corridors and end-user-driven demand (largest IT base). Hyderabad wins on near-term momentum (39% in 12 months Mar 2025–Mar 2026), GCC-led office demand, and entry-tier pricing. For pure investment ROI, Hyderabad and Bengaluru beat Mumbai; for prestige, liquidity and ultra-luxury, Mumbai is unmatched.
What infrastructure is coming to Mumbai in the next 2 years?
Five major catalysts in active commissioning. (1) Coastal Road Phase 2 (Bandra-Kandivali, ~19 km) — May 2026 target, full Marine Lines-Kandivali coastal expressway. (2) Metro Line 4 (Green Line, Wadala-Kasarvadavali, 32 km) — phased commissioning through Aug 2026, cuts central-suburb-to-Wadala/BKC commute by 50–75%. (3) NMIA (Navi Mumbai International Airport) — Phase 1 domestic May 2025, international July 2025, full operations by 2027. (4) GMLR (Goregaon-Mulund Link Road) — first 1.2 km flyover May 2026, twin tunnels under Sanjay Gandhi NP target 2028. (5) MMRDA Ring Road — ₹3 trillion master plan with target sub-60-min cross-city commute by 2029.
What's the rental yield in Mumbai in 2026?
City-wide average rental yield is 3.42% per Square Yards data — modest by national standards, typical for premium global cities. Apartments rent at ₹110/sqft monthly on average. Studios average ₹28,547/mo, 1 BHK ₹44,813, 2 BHK ₹83,561, 3 BHK ₹1.85 lakh, 4–6 BHK between ₹3.92 lakh and ₹4.19 lakh. Highest yields are in metro-anchored mid-segment IT belts (Mulund, Powai, Andheri East) at 3.5–4.5%. Premium areas (Worli, Bandra) yield lower (2.5–3%) but offer stronger capital preservation.
Which developers have the most active project pipeline in Mumbai?
Lodha Group leads on transaction value (largest by revenue), followed by Godrej Properties, Oberoi Realty, Hiranandani Developers, Kalpataru, Piramal Realty, Runwal Group, Shapoorji Pallonji, Rustomjee, and L&T Realty. Premium picks for luxury: Lodha (Cullinan, Worli World One), Oberoi (Sky City Borivali, Three Sixty West Worli), Piramal (Mahalaxmi, Revanta Mulund). Mid-segment leaders: Runwal, Shapoorji Pallonji, Tata Housing, Kalpataru. Q1 2026 saw a record 19,775 unit launches (Cushman & Wakefield) — up 25% QoQ — concentrated in Western Suburbs (25% share), Eastern Suburbs (20%), Navi Mumbai (17%) and Thane (15%).
Not sure which part of Mumbai suits you?
One call with our advisors covers areas, budgets, commute and the best live projects, with direct developer pricing.